
PRUHealth Signature is the most feature-rich plan from Prudential Health India. It offers up to ₹2 crore of cover, restoration from the very first claim and a loyalty boost of 100% every year. On paper, it is one of the strongest new health plans of 2026.
But strong features cost more. In this review, I check whether PRUHealth Signature is worth the extra premium over PRUHealth Edge, and how it stacks up against Niva Bupa ReAssure 3.0.
Quick verdict
- Best for buyers who want maximum cover growth without buying many add-ons.
- 100% yearly loyalty means ₹10 lakh can grow to ₹60 lakh over five years.
- Costs a little more than Edge; Edge can buy similar boosters as add-ons.
- New insurer, so the claims experience is still unproven.
List of Topic Covered
What is PRUHealth Signature?
PRUHealth Signature is the top variant of the PRUHealth product from Prudential HCL Health Insurance. It shares one policy wording with Protect and Edge. However, it comes with the best restoration, the fastest loyalty growth and longer pre-hospital cover as standard.
You can buy it as an individual policy or a family floater for up to six members, with a tenure of one to five years.
Why PRUHealth Signature matters
A serious illness rarely ends with one hospital stay. Cancer, for example, means surgery, chemo and follow-ups over months. So cover that refills from the first claim and grows every year is valuable.
Signature gives you both. In addition, it removes the need to stack several add-ons, which keeps the policy simple to understand at claim time.
PRUHealth Signature features explained
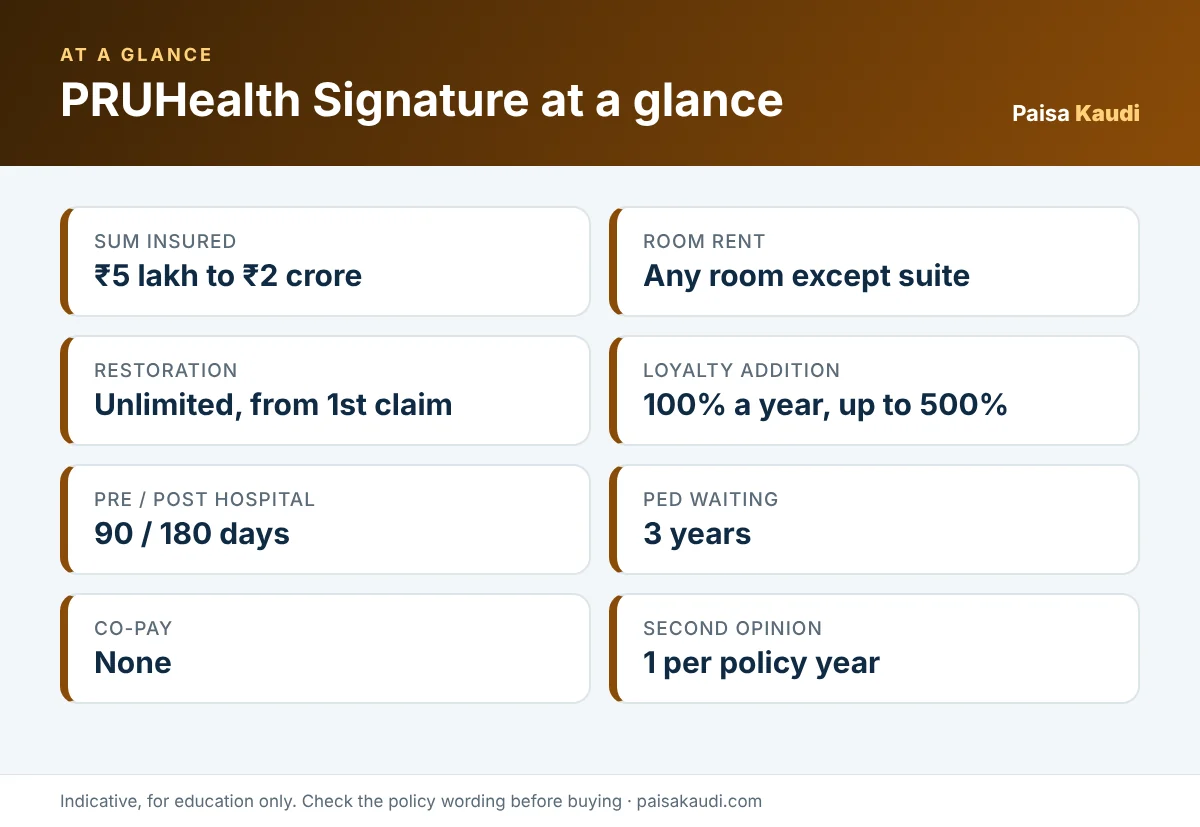
Cover from ₹5 lakh to ₹2 crore
This is the highest base cover among PRUHealth plans.
Any room except a suite
Single, twin-sharing or deluxe rooms are fine. ICU is covered up to the sum insured. However, a suite triggers proportionate deductions.
Restoration from the first claim
Your cover refills to 100% unlimited times a year, starting from the first claim. In effect, you get 2X protection from day one. Note that this is not an upfront doubling; it kicks in after you use the cover.
Loyalty addition of 100% a year
Your cover rises by 100% of the base every year, up to 500%, regardless of claims. For example, ₹10 lakh becomes ₹20 lakh in year two and can reach ₹60 lakh. Loyalty Addition Plus can push the ceiling to 1,000%.
Longer pre-hospital cover
Costs 90 days before admission and 180 days after discharge are covered. That is longer than Edge and Protect.
Wellness and extras
You get an annual health check-up, unlimited virtual GP calls, four psychologist sessions and one second medical opinion a year. Organ donor costs, home care, AYUSH and modern treatment are also covered up to the sum insured.
PRUHealth Signature eligibility and policy details
| Parameter | Details |
|---|---|
| Sum insured | ₹5 lakh to ₹2 crore |
| Adult entry age | 18 to 99 years |
| Child entry age | 91 days (floater) / 5 years (individual) |
| Family floater | Up to 6 members; children till 25 |
| Tenure | 1 to 5 years |
| Co-pay / sub-limits | None in base plan |
| Renewal | Lifelong |
| Migration and portability | Allowed, with continuity credits |
Waiting periods in PRUHealth Signature
- Initial: 30 days; accidents from day one.
- Specified diseases: 24 months.
- Pre-existing diseases: 36 months.
- Chronic Care QuickStart: waives waiting periods (except the first 30 days) for diabetes, hypertension, cholesterol, obesity and asthma.
PRUHealth Signature premium: real examples
| Profile (₹15 lakh, Zone 1, with Hospital Essentials) | First-year premium |
|---|---|
| Individual, age 25 | ₹14,394 |
| 2 adults (31, 32) | ₹22,061 |
| 2 adults + child (36, 35, 5) | ₹27,330 |
| 2 adults (62, 63) | ₹86,349 |
Compared with Edge at ₹15 lakh, Signature costs roughly ₹900–1,500 more for a young individual or couple. In return, you get first-claim restoration, 100% loyalty and 90-day pre-hospital cover. For many families, that is a fair trade.
Best add-ons for PRUHealth Signature
- Hospital Essentials Cover: consumables cover; strongly recommended.
- Chronic Care QuickStart: worth it if you have diabetes, BP or asthma.
- Critical Illness Cover: a lump sum on diagnosis, useful for income loss.
- Day 1 Instant Increase: available only when base cover is up to ₹5 lakh.
- Others: Air Ambulance, LongStay Allowance, Cancer Guard, Personal Accident and Child Protect.
PRUHealth Signature vs Edge: is the upgrade worth it?
| Feature | Edge | Signature |
|---|---|---|
| Max cover | ₹1 crore | ₹2 crore |
| Restoration | From 2nd claim (1st with add-on) | From 1st claim |
| Loyalty | 50%/yr to 100% | 100%/yr to 500% |
| Pre-hospital | 60 days | 90 days |
| Second opinion | Add-on | Included |
Edge can buy Restoration Plus and Loyalty Addition Plus to come close. So price both options before you decide. My PRUHealth plans comparison walks through this.
How to buy PRUHealth Signature online
- Pick your sum insured. Start with your city and family size. A metro family usually needs ₹15–25 lakh. PRUHealth Signature quotes change sharply with cover, so compare two or three amounts.
- Get a quote online. Open the PRUHealth Signature page on the Prudential Health website. Then enter ages, pincode and members. Pincode matters because premiums depend on the zone.
- Choose add-ons carefully. Add only what you will use. For example, Hospital Essentials (consumables) is useful for most buyers. A deductible or Select Network discount, however, suits only some people.
- Declare your health honestly. Mention every condition, medicine and past surgery. Hiding something is the most common reason for claim rejection later.
- Pay and save the documents. Pay online and claim the tax benefit under Section 80D. Then download the policy wording, schedule and e-card.
- Use the free-look period. You get a free-look window after you receive the policy. Read the wording during this time. If something does not suit you, cancel for a refund minus small charges.
You can also call Prudential Health on 1800 268 2000 for a quote.
How to claim under PRUHealth Signature
- Cashless claim: Go to a network hospital and show your e-card at the insurance desk. The hospital sends a pre-authorisation request. For planned surgery, inform the insurer at least 48–72 hours earlier.
- Emergency admission: Get admitted first. Then the hospital or a family member informs the insurer, ideally within 24 hours.
- Reimbursement claim: If the hospital is not in the network, pay the bill yourself. Then upload the claim form, bills, discharge summary and reports through the app or website.
- Track and follow up: Track the claim online. If it gets rejected unfairly, first complain to the insurer’s grievance team. After that, you can approach Bima Bharosa or the Insurance Ombudsman.
Pros and cons of PRUHealth Signature
What we like
- Cover up to ₹2 crore
- 2X protection from the first claim
- 100% yearly loyalty up to 500%, regardless of claims
- 90-day pre-hospital cover
- No co-pay or disease sub-limits
- Second medical opinion included
What to watch
- Costs more than Edge
- Suite room leads to deductions
- 3-year PED wait
- No claims, ICR or complaint data yet
Who should buy PRUHealth Signature?
- Families who want one strong policy instead of base plus top-up.
- People with a family history of cancer or heart disease who value fast-growing cover.
- Buyers who prefer fewer add-ons and simpler claims.
- Skip it if budget is tight. Then PRUHealth Edge with a super top-up may cost less.
Conclusion: is PRUHealth Signature worth it?
PRUHealth Signature is the strongest plan in the PRUHealth range. It delivers first-claim restoration, rapid cover growth and longer pre-hospital cover without stacking add-ons.
However, it comes from a brand-new insurer. So if claims history matters most to you, compare it with Niva Bupa or Aditya Birla Health before you buy PRUHealth Signature.
FAQs on PRUHealth Signature
What is the maximum cover under PRUHealth Signature?
The base sum insured goes up to ₹2 crore. With 100% loyalty addition up to 500%, the effective cover can grow much higher over the years.
Does PRUHealth Signature restore cover from the first claim?
Yes. It restores 100% of the base sum insured unlimited times a year, starting from the first claim.
Is there any co-pay in PRUHealth Signature?
No. The base plan has no mandatory co-pay and no standard disease-wise sub-limits.
What is the difference between PRUHealth Signature and Edge?
Signature offers up to ₹2 crore cover, restoration from the first claim, 100% yearly loyalty and 90-day pre-hospital cover. Edge goes up to ₹1 crore with 50% loyalty and second-claim restoration.
Can senior citizens buy PRUHealth Signature?
Yes, adults can enter up to age 99. However, a couple aged 62 and 63 pays around ₹86,000 for ₹15 lakh, so compare carefully.
Is PRUHealth Signature on your shortlist? Share your question in the comments below and I will reply.
Disclaimer: This article is for education only and is not insurance advice. Features, premiums and waiting periods are taken from public brochures, prospectus summaries and IRDAI data as of the update date. They can change. Always read the policy wording and prospectus before you buy. Paisa Kaudi is not an insurance intermediary
1 thought on “PRUHealth Signature Review 2026: Rs 2 Crore Cover, 2X Restoration and Verdict”