
India has eight standalone health insurance companies: insurers that sell only health cover, not motor or home insurance. They range from Star Health, the first and largest, to Prudential Health India, which opened in August 2026.
This guide lists every standalone health insurer, compares their latest IRDAI claim data, and points you to their best plan. Each name links to a full review, so you can go deeper on the ones that fit you.
Quick picks
- Largest network and widest plan range: Star Health.
- Balanced flagship plan with unlimited recharge: Care Health.
- Strong features and lock-in pricing: Niva Bupa.
- Wellness rewards that cut premium: Aditya Birla Health.
- Newest, feature-rich but unproven: Prudential Health.
List of Topic Covered
What are standalone health insurance companies?
A standalone health insurer (SAHI) is licensed by IRDAI to write only health, personal accident and travel cover. In contrast, general insurers such as HDFC ERGO or ICICI Lombard also sell car, home and business insurance.
Because health is their only business, SAHIs tend to offer more plan types, more add-ons and in-house claim teams. However, being specialised does not automatically mean better claims. So you still need to check the data.
Why choosing the right standalone health insurer matters
Your plan’s features matter only if the insurer pays fairly and quickly. A plan with great features but a slow claim desk can still leave you with a big bill at discharge.
That is why this list puts claim data next to each company. In addition, network size in your city decides whether you get cashless treatment or have to pay first and claim later.
List of standalone health insurance companies in India (2026)
| Insurer | Started | Backed by | Network* | Flagship plan |
|---|---|---|---|---|
| Star Health & Allied | 2006 | Listed company | 14,000+ | Super Star |
| Care Health | 2012 | Religare group (promoter) | 11,000+ | Care Supreme |
| Niva Bupa | 2010 | Bupa (UK), listed | 10,000+ | ReAssure 3.0 |
| Aditya Birla Health | 2016 | Aditya Birla Capital | 12,000+ | Activ One Max |
| ManipalCigna | 2014 | Manipal Group + Cigna | Varies by source | Sarvah |
| Galaxy Health | 2024 | TVS family + V. Jagannathan | 7,000+ | Galaxy Marvel / Promise |
| Narayana Health | 2023 | Narayana hospital group | Plan-dependent | Aditi / Arya |
| Prudential Health | 2026 | Prudential plc + HCL | 12,000+ | PRUHealth Edge |
*Network figures are as published by insurers or leading aggregators and change often. Always check your own pincode.
Claim data: how standalone health insurance companies compare
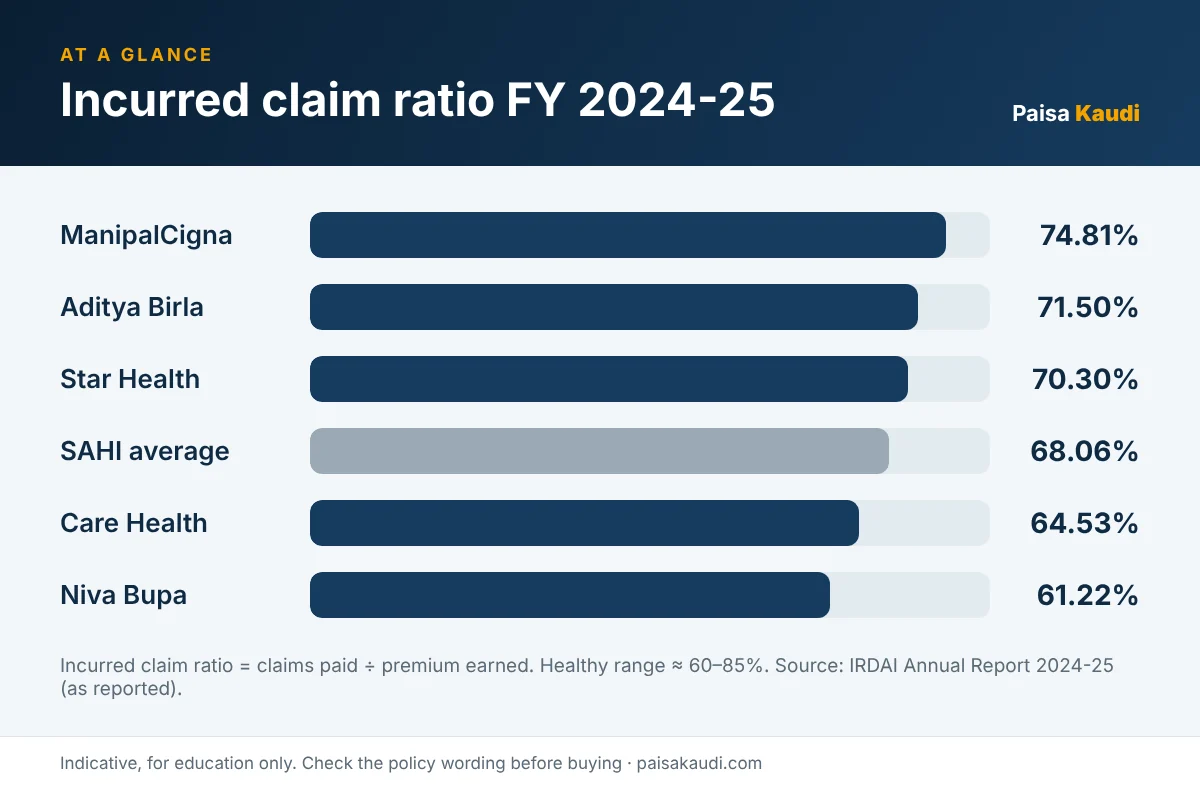
Two numbers tell you most of what you need about an insurer. First, the incurred claim ratio (ICR) shows how many rupees it paid in claims for every ₹100 of premium. A very low ICR can hint at strict claim practices, while a very high one can strain finances. A range of roughly 60–85% is healthy. Second, the complaints per 10,000 claims shows how often customers are unhappy.
Claim settlement ratio (CSR) by count is popular, but sources report very different CSR figures for the same insurer and year. So I lean on ICR from the IRDAI annual report, and I treat CSR as a secondary check.
| Insurer | ICR FY 2024-25 | Complaints (FY 2024-25) | What it tells you |
|---|---|---|---|
| ManipalCigna | 74.81% | Not widely reported | Highest payout ratio among SAHIs |
| Aditya Birla Health | 71.50% | Low (per reports) | Healthy balance |
| Star Health | 70.30% | 12,186 (about 52 per 10,000 claims) | Big scale, high complaint count |
| Care Health | 64.53% | 4,423 | Moderate payout |
| Niva Bupa | 61.22% | 3,983 (about 43 per 10,000 claims) | Lowest ICR among large SAHIs |
| Galaxy / Narayana / Prudential | Not yet available | Too new | No track record yet |
| Standalone average | 68.06% | – | Benchmark |
ICR figures are from the IRDAI annual report 2024-25 as reported by PolicyEra and HonestMoney. The overall non-life industry ICR was 82.88%, according to Business Standard.
Best plan from each standalone health insurer
| Insurer | Plan | Cover | Standout feature |
|---|---|---|---|
| Star Health | Super Star | ₹5 lakh to unlimited | Freeze Your Age until first claim |
| Care Health | Care Supreme | ₹5 lakh – 1 crore | Unlimited automatic recharge |
| Niva Bupa | ReAssure 3.0 | ₹5 lakh to unlimited | Lock the Clock + Booster+ |
| Aditya Birla | Activ One Max | ₹5 lakh – 2 crore | HealthReturns wellness rewards |
| ManipalCigna | Sarvah | Up to ₹1 crore | Unlimited restoration, Gullak bonus |
| Galaxy | Marvel | ₹5 lakh – 2 crore | No room rent limit or sub-limits |
| Narayana | Arya | ₹25 lakh to unlimited | Premium refund on surgery |
| Prudential | PRUHealth Edge | ₹5 lakh – 1 crore | 50% yearly loyalty, any room |
Want head-to-heads? Read Star Health vs Care Health, Care Supreme vs ReAssure 3.0, PRUHealth Edge vs Care Supreme and PRUHealth Signature vs ReAssure 3.0.
Standalone vs general insurers: which is better?
What we like
- More health plan choices and add-ons
- In-house claim teams at most SAHIs
- Specialised products for seniors, PED and diseases
What to watch
- Some SAHIs have high complaint counts
- General insurers like HDFC ERGO often post higher ICR
- New SAHIs have no track record
In short, judge the insurer by its data and the plan by its wording, not by whether it is standalone.
How to choose among standalone health insurance companies
- Shortlist by data. Prefer insurers with ICR in the 60–85% range and lower complaints.
- Check your city network. Cashless access near home matters most.
- Compare the flagship plan. Look at room rent, restoration, bonus and co-pay.
- Price the final policy. Include the add-ons you need.
- Read the wording. Especially exclusions and waiting periods.
Conclusion: the best standalone health insurance companies for you
No single insurer is best for everyone. Among standalone health insurance companies, Star Health offers reach, Care and Niva Bupa offer strong flagship plans, and Aditya Birla rewards healthy habits. Meanwhile, Galaxy, Narayana and Prudential bring fresh products but no track record yet.
Start with the two insurers that have strong data and a good hospital near you. Then compare their flagship plans. Finally, read the reviews linked above before you buy.
FAQs on Standalone Health Insurance Company
How many standalone health insurance companies are there in India?
There are eight: Star Health, Care Health, Niva Bupa, Aditya Birla Health, ManipalCigna, Galaxy Health, Narayana Health and Prudential Health India.
Which is the oldest standalone health insurer in India?
Star Health and Allied Insurance, which started in 2006.
Which standalone health insurer has the highest claim ratio?
For FY 2024-25, ManipalCigna reported the highest ICR among standalone insurers at about 74.8%, followed by Aditya Birla Health and Star Health.
Is a standalone health insurer better than a general insurer?
Not automatically. Standalone insurers offer more health plans, but you should compare claim ratios, complaints and network for each company.
Which is the newest standalone health insurer?
Prudential Health India, a Prudential plc and HCL Group joint venture, which started on 20 August 2026.
Which standalone health insurer do you use, and how was your claim experience? Share your question in the comments below and I will reply.
Disclaimer: This article is for education only and is not insurance advice. Features, premiums and waiting periods are taken from public brochures, prospectus summaries and IRDAI data as of the update date. They can change. Always read the policy wording and prospectus before you buy. Paisa Kaudi is not an insurance intermediary.
3 thoughts on “Standalone Health Insurance Companies in India 2026: Full List, Claim Data and Best Plans”