
El Niño health insurance is suddenly a real question for Indian families. The World Health Organization (WHO) has placed India among the countries facing a high or very high health risk from the 2026 El Niño. So, will your policy pay if you fall sick? This guide explains the alert, the diseases to watch, the IRDAI rules and the plans that cover you.
List of Topic Covered
Why is it called El Niño?
El Niño is Spanish for “the little boy”. Long ago, fishermen in Peru saw the sea near their coast turn warm every few years. Since this usually happened around Christmas, they named it after the Christ child.
El Niño is a warming of the Pacific Ocean that shifts rain and heat across the world. For India, it often means a weaker monsoon and hotter summers.
What did WHO say about El Niño?
First, the basics. WHO has activated a Grade 3 response, its highest emergency level, for El Niño. The response runs from October 2026 to September 2027.
Here are the key dates:
- 5 September 2026: WHO released its global health risk assessment.
- 2 November 2026: WHO issued its preparedness and response plan.
- First six months: WHO needs about $35 million for early work.
India is not alone. Bangladesh, Nepal, Bhutan, Sri Lanka and the Maldives are also on the risk list. In addition, the World Meteorological Organization says this El Niño is very strong and may last into 2027.
However, WHO is clear that El Niño does not cause disease by itself. Instead, it acts as a “risk multiplier”. It changes heat and rain patterns, and that helps diseases spread.
El Niño health risks India could face
WHO has flagged five main risks for India.
- Heatwaves: Dehydration, heat exhaustion and heatstroke.
- Dengue: Rated high or very high risk. Malaria is also a concern in parts of the Northeast.
- Leptospirosis and water-borne infections: These rise after floods, heavy rain and poor sanitation.
- Malnutrition: Weak rain and drought can hit food supply.
- Hospital strain: Medicine shortages and gaps in care for chronic patients.
Who is most at risk?
Some groups need extra care. For example, children under five, pregnant women and older adults are more exposed. People with heart, kidney or lung problems also face higher heat risk. Finally, outdoor workers, slum residents and remote communities have less access to water, cooling and doctors.
Does El Niño health insurance actually exist?
Here is the short answer. There is no special “El Niño policy” in India. Instead, your normal health plan covers most El Niño illnesses, as long as you need hospital care.
The table below shows how each problem is usually treated.
| Health problem | Covered by regular health insurance? | What to watch |
| Dengue, malaria, chikungunya | Yes, on hospitalisation | 30-day initial waiting period on new policies |
| Heatstroke, severe dehydration | Yes, if admitted | Doctor must record heat as the cause |
| Leptospirosis, typhoid, diarrhoea | Yes, on hospitalisation | Usually needs 24-hour admission |
| Kidney or heart complications | Yes | Pre-existing disease rules apply |
| Malnutrition | Only hospital treatment | Food and supplements are not covered |
| OPD visits and tests | Only in plans with OPD cover | Check your policy wording |
Experts note that heatstroke is rarely listed as a separate risk. Even so, hospital claims for heatstroke, dehydration or kidney stress are usually paid unless the policy excludes them. As a result, good medical records matter more than anything else.
What is the IRDAI’s take?
As of 14 November 2026, we could not find any El Niño-specific circular from IRDAI. However, its existing rules already protect you. Here are the ones that matter most.
1. A standard mosquito-disease policy: Mashak Rakshak
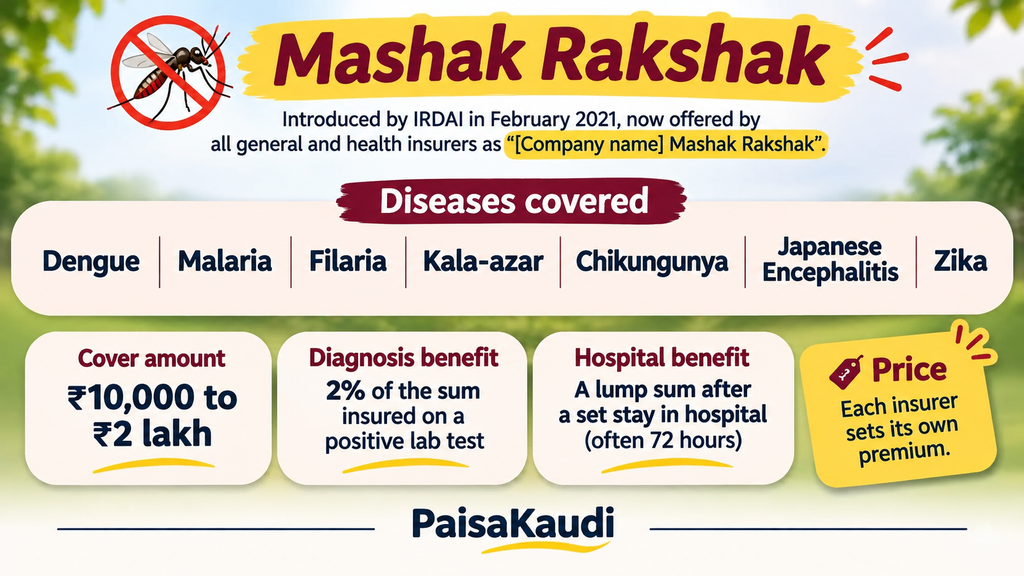
In February 2021, IRDAI asked all general and health insurers to offer a Standard Vector Borne Disease Health Policy. Each insurer sells it as “[Company name] Mashak Rakshak”.
- Diseases covered: Dengue, malaria, filaria, kala-azar, chikungunya, Japanese encephalitis and Zika.
- Cover amount: ₹10,000 to ₹2 lakh.
- Diagnosis benefit: 2% of the sum insured on a positive lab test.
- Hospital benefit: A lump sum after a set stay in hospital (often 72 hours).
- Price: Each insurer sets its own premium.
2. Faster cashless claims
Under the IRDAI Master Circular of 29 May 2024, insurers must decide cashless requests within 1 hour. Also, final discharge approval must come within 3 hours of the final bill.
3. Waiting periods and other rules
- Initial wait: New policies usually skip illness claims for the first 30 days. Accidents are covered from day one.
- Pre-existing diseases: The wait is capped at 3 years.
- Moratorium: After 5 years of cover, claims cannot be rejected for non-disclosure, except for fraud.
- No age cap: Insurers cannot refuse you only because of age.
- No GST: Individual and family health premiums have been GST-free since 22 September 2025.
- AYUSH: Ayurveda and other AYUSH treatments are covered too.
El Niño health insurance: companies that cover these illnesses
In short, El Niño health insurance is mostly your regular plan. Almost every health insurer covers dengue, malaria, heatstroke and leptospirosis under regular plans. Then, for a cheap top-up, you can add a disease-specific plan.
Small mosquito-disease plans
| Plan | Sum insured | Waiting period | Indicative premium |
| ICICI Lombard Mashak Rakshak | ₹10,000 – ₹2 lakh | 15 days* | Low; varies by cover |
| HDFC ERGO Dengue Care | ₹50,000 – ₹1 lakh | 15 days | From about ₹310/year |
| Bajaj General M-Care | ₹10,000 – ₹75,000 | 15 days | Low; varies by cover |
| Shriram Vector Care | Up to ₹75,000 | 15 days | Low; varies by cover |
| Future Generali Vector Care | Up to ₹75,000 | 15 days | Low; varies by cover |
| Dengue Cover via Bajaj Markets | ₹50,000 | Per policy | ₹299/year |
*Standard IRDAI product; confirm with the insurer. Overall, these plans usually cost between about ₹49 and ₹682 a year.
Top 10 full health plans (better long-term choice)
India has two kinds of health insurers. Standalone health insurers sell only health cover. General insurers also sell motor and travel cover. Both kinds cover dengue, malaria, heatstroke and leptospirosis on hospitalisation.
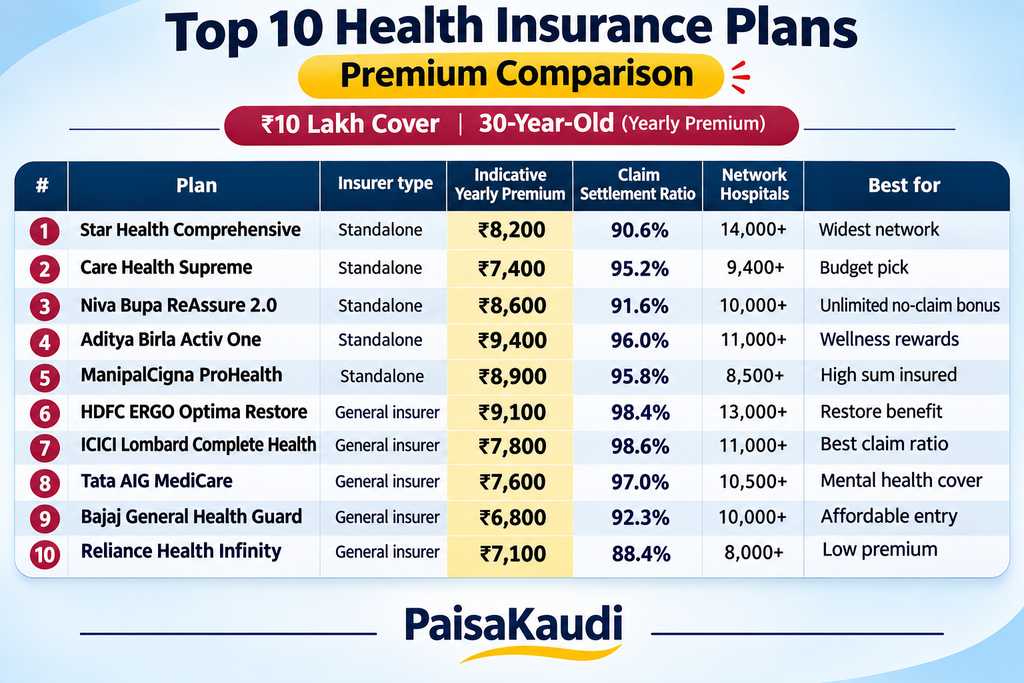
Top 10 health insurance premium comparison
| # | Plan | Insurer type | Indicative yearly premium | Claim settlement ratio | Network hospitals | Best for |
| 1 | Star Health Comprehensive | Standalone | ₹8,200 | 90.6% | 14,000+ | Widest network |
| 2 | Care Health Supreme | Standalone | ₹7,400 | 95.2% | 9,400+ | Budget pick |
| 3 | Niva Bupa ReAssure 2.0 | Standalone | ₹8,600 | 91.6% | 10,000+ | Unlimited no-claim bonus |
| 4 | Aditya Birla Activ One | Standalone | ₹9,400 | 96.0% | 11,000+ | Wellness rewards |
| 5 | ManipalCigna ProHealth | Standalone | ₹8,900 | 95.8% | 8,500+ | High sum assured |
| 6 | HDFC ERGO Optima Restore | General insurer | ₹9,100 | 98.4% | 13,000+ | Restore benefit |
| 7 | ICICI Lombard Complete Health | General insurer | ₹7,800 | 98.6% | 11,000+ | Best claim ratio |
| 8 | Tata AIG MediCare | General insurer | ₹7,600 | 97.0% | 10,500+ | Mental health cover |
| 9 | Bajaj General Health Guard | General insurer | ₹6,800 | 92.3% | 10,000+ | Affordable entry |
| 10 | Reliance Health Infinity | General insurer | ₹7,100 | 88.4% | 8,000+ | Low premium |
Note: All premiums are indicative. Your price depends on age, city, health and add-ons. Claim settlement ratios come from the IRDAI annual report and change every year. Always get a live quote before you buy.
Which El Niño health insurance option should you pick?
The right choice depends on what you already have.
- No health cover yet: Buy a full plan first. A ₹5 lakh to ₹10 lakh cover handles dengue, heatstroke and kidney problems.
- Only office cover: Then add a personal plan, since group cover ends when you leave the job.
- Already insured: A Mashak Rakshak or dengue plan is a cheap extra. It pays cash for costs your main plan skips.
- Parents above 60: Look at senior plans. Remember, IRDAI has removed the age cap.
Also, low-income families should check Ayushman Bharat PM-JAY, which offers free hospital cover at listed hospitals.
5 tips to avoid El Niño health insurance claim rejection
- Buy now. The 30-day initial wait means a policy bought during an outbreak may not help at once.
- Keep lab reports. A positive NS1, ELISA or malaria test proves your claim.
- Ask the doctor to write the cause. For example, “heatstroke” or “dengue with low platelets”.
- Tell the insurer early. Inform them within 24 hours of an emergency admission.
- Read exclusions. Check room-rent limits and co-pay before you need them.
Conclusion: Make El Niño health insurance part of your plan
El Niño will bring heat, mosquitoes and floods to many parts of India through 2027. Fortunately, regular health plans already cover most of these illnesses. So, your best El Niño health insurance strategy is simple. Keep a solid base policy, add a low-cost mosquito-disease cover, and buy before the next outbreak.
Above all, prevention still comes first. Drink water, avoid peak-noon sun, and stop mosquitoes from breeding at home.

Have you checked whether your policy covers dengue or heatstroke? Share your experience in the comments below.