
LIC New Jeevan Dhara-II is a deferred pension plan. In simple terms, you pay now (once or every year), wait 1 to 15 years, and then get a guaranteed pension for the rest of your life. Also, the pension rate is locked on the day you buy. Based on LIC’s own examples, however, the return works out to only about 5.5% to 6.5% a year before tax.
List of Topic Covered
Quick facts On LIC New Jeevan Dhara-II
| Item | Details |
| Plan name | LIC’s New Jeevan Dhara-II |
| Plan no. / UIN | 892 / 512N398V01 |
| Plan type | Non-Par, Non-Linked, Individual, Savings, Deferred Annuity |
| Launch date | 19 October 2026 |
| Bonus | No; all benefits are guaranteed |
| Predecessor | Jeevan Dhara-II (Plan 872) |
| Where to buy | LIC agents, brokers, corporate agents, or online at licindia.in (not through POSP or CSC) |
LIC New Jeevan Dhara-II Key Features
- First, the pension rate is guaranteed at the start and paid for life.
- You can pay once (Single Premium) or every year (Regular Premium).
- Also, you can choose single life or joint life (husband-wife, parent-child, siblings and more).
- The pension then starts after 2 to 15 years (Regular) or 1 to 15 years (Single).
- In addition, the pension can be paid monthly, quarterly, half-yearly or yearly.
- If you die during the waiting period, your family gets 105% of premiums paid.
- Besides, a top-up lets you add more money during the waiting period (minimum ₹50,000 each time) to raise the pension.
- Similarly, the liquidity option lets you take up to 60% of premiums back as a lump sum after 5 years of pension (return-of-premium options).
- Also, you get a higher pension for bigger premiums, online purchase and existing LIC policyholders.
11 annuity options in LIC New Jeevan Dhara-II
| Option | Premium type | Pension for | What the family gets on death after pension starts |
| 1 | Regular | Single life | Nothing |
| 2 | Regular | Single life | 100% of premiums paid |
| 3 | Regular | Single life + 50% of premiums back at age 75 | Premiums paid minus amount returned |
| 4 | Regular | Single life + 100% of premiums back at age 75 | Premiums paid minus amount returned |
| 5 | Regular | Single life + 50% of premiums back at age 80 | Premiums paid minus amount returned |
| 6 | Regular | Single life + 100% of premiums back at age 80 | Premiums paid minus amount returned |
| 7 | Regular | Single life + 5% of premiums back each year from age 76 to 95 | Premiums paid minus amount returned |
| 8 | Regular | Joint life (100% to survivor) | Nothing after both die |
| 9 | Regular | Joint life (100% to survivor) | 100% of premiums paid, after both die |
| 10 | Single | Single life | 100% of purchase price |
| 11 | Single | Joint life (100% to survivor) | 100% of purchase price, after both die |
However, the option can’t be changed later, so choose carefully.
Eligibility options in LIC New Jeevan Dhara-II
| Condition | Details |
| Minimum entry age | 18 years |
| Maximum entry age | 70 minus deferment period (Options 2, 5, 6, 7, 9, 10, 11); 65 minus deferment period (Options 1, 3, 4, 8) |
| Pension start (vesting) age | Pension must start between age 30 and 70 (30 and 65 for Options 1, 3, 4 and 8) |
| Deferment period | 2 to 15 years (Regular); 1 to 15 years (Single) |
| Premium paying term | Same as deferment period (Regular); once (Single) |
| Minimum yearly premium | From ₹11,000 (Option 1, 10+ years wait, age below 55) up to ₹1,92,000 for short waits |
| Minimum single premium | ₹1,01,000 to ₹2,17,000, depending on option, age and wait |
| Minimum pension | ₹1,000 a month / ₹12,000 a year |
| Maximum premium | No limit (subject to underwriting) |
Worked example of LIC New Jeevan Dhara-II
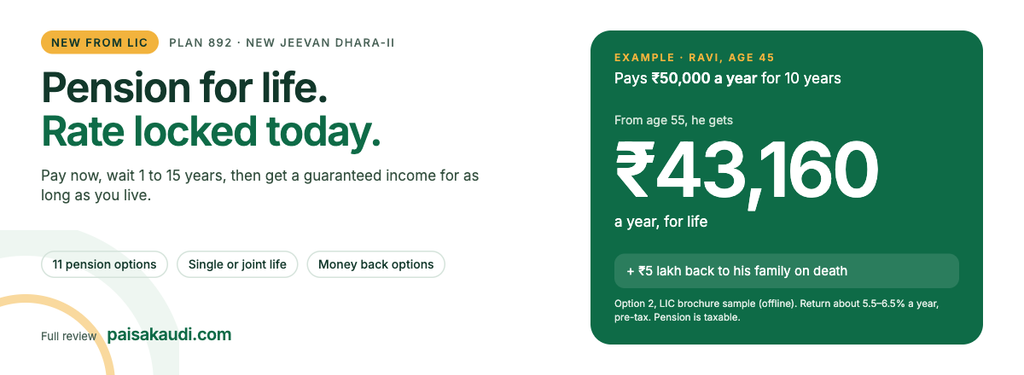
Let’s understand this plan with the help of an example. Suppose 45 years old Ravi is paying ₹50,000 a year for 10 years (₹5 lakh in total) in this plan. So his pension starts at 55. According to LIC’s sample, his yearly pension (offline, new customer) is:
| Option | Pension starts after 5 years | Pension starts after 10 years | Pension starts after 15 years |
| 1: Life annuity, nothing back | ₹19,950 | ₹51,975 | ₹1,01,215 |
| 2: Life annuity + premiums back on death | ₹16,805 | ₹43,160 | ₹83,100 |
| 4: + 100% premiums back at 75 | ₹15,240 | ₹38,415 | ₹72,630 |
| 7: + 5% premiums back each year 76 to 95 | ₹16,345 | ₹41,770 | ₹80,030 |
| 8: Joint life, nothing back | ₹18,125 | ₹45,990 | ₹86,840 |
| 9: Joint life + premiums back | ₹16,590 | ₹41,470 | ₹77,130 |
Note that joint-life figures assume a 40-year-old spouse. Also, the total paid differs by column: ₹2.5 lakh (5 years), ₹5 lakh (10 years) and ₹7.5 lakh (15 years).

For example, with Option 2 and a 10-year wait, Ravi gets ₹43,160 a year (about ₹3,450 a month after the monthly-mode adjustment) for life. Then, when he dies, his family gets back the ₹5 lakh he paid.

Single premium example: if Ravi instead pays ₹5 lakh once at 45 under Option 10, he gets ₹60,300 a year from age 55. In addition, ₹5 lakh goes to his family on death.
The real return in LIC New Jeevan Dhara-II
I worked out the return (IRR) from LIC’s sample figures, assuming the yearly pension is paid at the end of each year. As you can see below, the return depends on how long you live.
| Ravi lives to | Option 1 (10-yr wait) | Option 2 (10-yr wait) | Option 10 single premium (10-yr wait) |
| 75 | 4.9% | 5.6% | 5.7% |
| 80 | 5.7% | 5.8% | 6.0% |
| 85 | 6.2% | 5.9% | 6.1% |
| 90 | 6.4% | 5.9% | 6.2% |
These are pre-tax returns, and the pension is taxed as income at your slab rate. In comparison, the Senior Citizen Savings Scheme pays 8.2% and the Post Office Monthly Income Scheme pays 7.4% (October to December 2026).

Still, you can raise these figures a little. For instance, buying online adds 2% to 4% to the pension rate, and existing LIC policyholders get 0.25% to 0.5% more. Also, premiums of ₹50,000+ a year (or ₹3 lakh+ single) get a higher-premium incentive.
Useful options in LIC New Jeevan Dhara-II
- Top-up annuity: during the waiting period, you can pay extra (₹50,000 minimum) to buy more pension at the rates prevailing then.
- Liquidity option (Options 2, 9, 10, 11): after 5 years of pension, you can withdraw part of your money, up to 3 times and up to 60% of premiums in total. However, pension and death benefit reduce in the same proportion.
- Advance annuity (Options 9, 11): when one spouse dies, the survivor can take up to 5 years of pension in advance as a lump sum.
- Death benefit payout: your nominee can take it as a lump sum, as a new pension, or in instalments over 5, 10 or 15 years.
- For a dependent with disability (Divyangjan): under Option 10, with a minimum of ₹50,000, the death benefit buys a lifelong pension for the disabled dependent.
- NRI / UK pension transfer: in addition, Options 10 and 11 can be bought as a QROPS.
Surrender, loan, lapse and revival in LIC New Jeevan Dhara-II
| Situation | What happens |
| Surrender in year 1 | Nothing (Regular Premium) |
| Surrender during the waiting period | Guaranteed value from year 2: 30% to 50% of premiums for 5+ year waits in early years, rising to 90%; or the special surrender value, if higher |
| Surrender after pension starts | Options 1 and 8: not allowed. Others: 90% of premiums minus pension already received, or special value if higher |
| Single premium surrender | Guaranteed value is 75% of the purchase price during the waiting period |
| Loan | Available under the return-of-premium options, within the surrender value |
| Stop paying (after 1 year) | Policy becomes paid-up with a reduced pension |
| Revival | Within 5 years, with interest (9.5% for 2026-27) |
LIC itself warns that early surrender can mean a big loss. Therefore, treat this as money you won't touch.
Other conditions in LIC New Jeevan Dhara-II
- The pension is paid in arrears, so the first payment comes a month, quarter, half-year or year after the pension starts.
- Premium modes are yearly, half-yearly, quarterly, monthly (NACH) or salary deduction.
- Also, the grace period is 30 days (15 days for monthly).
- Tax: premiums may qualify under Section 80CCC (old regime, within the ₹1.5 lakh limit). However, the pension is fully taxable, so check with your tax advisor.
New Jeevan Dhara-II vs other retirement income options
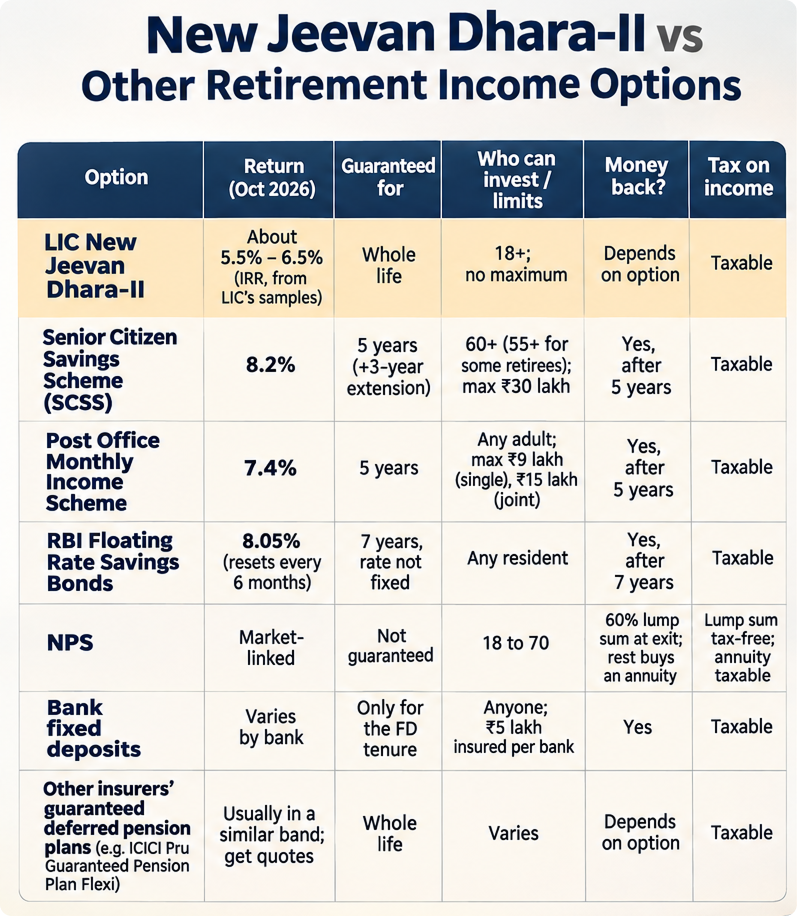
The honest view: SCSS, POMIS and RBI bonds pay more today. But they last only 5 to 7 years, and then you must reinvest at whatever rate exists at that time. In contrast, LIC New Jeevan Dhara-II guarantees today's rate for life, however long you live. In other words, that guarantee is what you pay for with the lower return.

So the smart order for most retirees is: first fill SCSS and POMIS limits, then use an annuity like this for the part of expenses you want guaranteed for life.
LIC New Jeevan Dhara-II: pros and cons
Who should buy LIC New Jeevan Dhara-II
- People aged 45 to 60 without a pension, such as private-sector employees, self-employed people and business owners, who want a fixed income for life after retirement.
- Very conservative investors who never want to depend on markets or interest rate changes.
- Couples who want the pension to continue to the surviving spouse (Options 9 and 11).
- Retirees who have already filled SCSS and POMIS limits and want more guaranteed income.
- Parents of a child with a disability, because Option 10 can provide a pension for the child after they are gone.
- People in good health from long-lived families, since the longer you live, the better the return.
Who should skip it
- People under 40. Over 15+ years, equity mutual funds, NPS or PPF are likely to grow your money faster.
- Anyone who may need this money back in an emergency.
- People who haven’t used SCSS, POMIS or RBI bonds yet, because those pay more.
- Also, people in the 30% tax slab who want the most post-tax income.
Verdict
Overall, LIC New Jeevan Dhara-II is a safe, flexible pension plan, but not a high-return one. Its real value is the lifelong guarantee, which no small savings scheme offers. So use it for part of your retirement money, not all of it. For most buyers, Option 2 (or Option 10 for a lump sum) is the balanced choice, because it gives a steady pension plus money back to the family. Finally, buy online for a higher pension rate.
Disclaimer: This review is based on LIC’s sales brochure (UIN 512N398V01). Returns are my calculations from LIC’s sample figures and are pre-tax. This is for information only, not financial advice.